Afterpay: Pay over time
AfterpayShoppingVerified
- 70.25K Reviews
- 4.0
- Downloads
- 10,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
I tend to notice the internet connection most when a shopping app is supposed to make a purchase feel simple. Browsing can be leisurely, but checkout has a clock-like pressure: the cart is ready, the payment choice needs to load, and I want to know what I’m agreeing to before I tap. Afterpay: Pay over time is built around that moment, letting shoppers use a buy-now-pay-later option through the app and participating retailers. It can make a planned purchase easier to fit into a budget, but the payment schedule still deserves the same attention as the item itself.
When a steady connection matters
In my experience, the most important online moments are account setup, retailer checkout, and checking the schedule afterward. Those steps depend on the service being reachable, so I would not treat the app as a substitute for having a reliable way to review a purchase and its upcoming payments. If a checkout page stalls or an approval step takes longer than expected, I prefer to pause and confirm what happened before trying again; repeated taps can create uncertainty about whether an order was submitted.
That makes a practical difference for anyone shopping on a weak public Wi-Fi connection or while moving between networks. I’d wait until the page has settled before switching apps, and I’d check the order and payment details once the connection is stable. The convenience is most useful when it gives me a clear view of the commitment, not when it encourages a rushed tap just to get through checkout.
Using it on the move
Shopping from a phone suits the service because the decision, payment choice, and follow-up reminders can all happen in a mobile routine. The app is free, is developed by Afterpay, and is listed for everyone; its current version is 1.131.0, with Android support beginning at version 7.0. Those details make it accessible to many phone owners, though the actual shopping experience still depends on the retailer and the connection available at the time.
A useful everyday case is replacing a necessary item online when payday is close but not here yet. I’d first compare the total with what I can comfortably cover, then check the dates and amounts in the payment schedule before confirming. If I’m shopping while commuting, I’d rather save the decision for a moment when I can read the checkout screen carefully than try to manage a payment commitment between interruptions.
What to do when something goes wrong
Network hiccups are only one source of friction. A retailer’s checkout can behave differently from another retailer’s, and switching between the store and the payment app may interrupt the flow. If a payment or order status is unclear, I would avoid assuming that an incomplete screen means nothing happened. Reopen the relevant account or retailer page once the connection returns and look for a clear status before making another attempt.
That cautious approach also helps with returns or changed plans. A return is not the same as an immediate change to a payment schedule, so I’d keep the order details and follow the retailer’s return process, then check the account for any update. The app is useful for visibility, but it cannot make a retailer’s stock, delivery, or return handling instant. For anything time-sensitive, I’d confirm the purchase directly with the retailer as well.
Other Stories to Read



Making mobile data work for you
For a data-conscious routine, I’d use Wi-Fi for browsing larger retailer catalogs and keep mobile data for checking a schedule or making a decision when needed. More importantly, I’d avoid opening several shopping sessions and losing track of which cart I chose to finance. A short pause to review the item, total, and due dates is a better safeguard than relying on notifications alone; reminders can help, but they should not replace a personal calendar or budget check if you have several obligations to track.
It also helps to separate “I can split this payment” from “I can afford this purchase.” Before confirming, I’d ask whether the item is necessary now, whether the installments fit alongside bills already due, and whether I could still cover them if my plans change. That little check is especially useful when browsing late at night or following a tempting sale, when the lower first payment can make the full cost feel less immediate.
Breaking Down the Basics
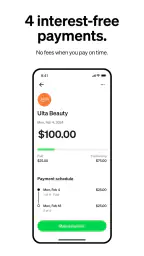
First off, let’s talk about how Afterpay works. The concept is simple: you make a purchase at a participating retailer, and instead of paying the full price upfront, you split the total into four interest-free installments. It’s like having a financial fairy godmother, except you still have to pay eventually. The payments are due every two weeks, making it easier to budget and manage your expenses without interest fees nibbling away at your funds.
One thing I immediately appreciated was the straightforward setup. After downloading the app, I was quickly guided through creating an account and linking my preferred payment method. No hoops to jump through, just straight to the point.
Shopping Experience
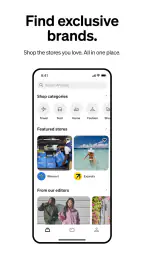
The real magic happens when you start shopping. With a plethora of partnered retailers, from fashion to electronics, there’s a little something for everyone. I found it particularly handy during a recent online shopping spree. Once you’ve filled your virtual cart, selecting Afterpay as your payment method at checkout is as easy as pie. The app then sends you a payment schedule and reminders, so you’re never blindsided by an upcoming payment.
What I loved was the seamless integration. There’s no need to switch between apps or fill out lengthy forms each time you want to make a purchase. It’s all baked into the shopping experience, making it feel less like a financial commitment and more like a convenient way to shop.
Managing Your Payments
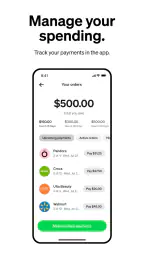
Alright, let’s get real for a second. The idea of "buy now, pay later" can be both exciting and daunting. Afterpay mitigates this by offering an intuitive dashboard where you can track your spending and payment schedules. The app sends timely notifications before each payment is due, which for a forgetful person like me, is a lifesaver.
If you ever feel the need to pay off a purchase early, the app gives you that flexibility, too. It’s a small feature, but it offers peace of mind knowing you’re not locked into a rigid payment plan.
Choosing it over other ways to pay
Compared with paying the full amount by debit card, this approach spreads the cost into scheduled payments, which may help with cash flow but adds dates to remember. A credit card may offer different repayment options and benefits depending on the card, while a budgeting app can help you plan without creating a new purchase commitment. I see Afterpay as a checkout choice, not a replacement for those broader tools. If I already have the money set aside, paying upfront is simpler; if I need a longer repayment horizon, I’d compare options carefully rather than assuming a short installment plan is automatically the best fit.
The app is most useful when a purchase is already planned and the installments fit comfortably around regular expenses. I would skip it for impulse buys, for essentials I can’t reliably afford, or whenever tracking several due dates would add stress. The first payment is only part of the cost, so I’d judge affordability by the whole purchase and the timing of every installment, not by the amount due at checkout.
A practical way to keep control
One habit I’d recommend is checking the schedule immediately after placing an order, then putting the due dates somewhere I already review, such as a calendar or monthly budget. That gives me a second point of reference if a reminder is missed or I’m away from the app. When making more than one purchase, I’d also look at all upcoming installments together; separate orders can seem manageable individually while their dates cluster in the same week.
For a realistic example, imagine ordering a replacement pair of shoes online shortly before a busy month. I’d confirm the retailer accepts Afterpay, check the complete cart total, and compare the payment dates with rent, bills, and other planned spending. If the schedule still leaves room, splitting the cost may be convenient. If it makes the rest of the month tight, I’d wait or choose a lower-cost option instead. The app can arrange payments, but it cannot make that budget decision for me.
Why It Stands Out
So, what makes Afterpay: Pay over time stand out in a sea of payment apps? For starters, it’s the lack of interest. Many buy now, pay later services come with hidden fees or interest rates that can catch you off guard. Here, what you see is what you pay—no surprises lurking in the fine print.
Moreover, it’s the community vibe. Afterpay has built a loyal user base, and it’s easy to see why. The app encourages responsible spending and offers support if you’re ever in a bind. It’s not just a transaction tool; it feels like a financial partner that wants to see you succeed.
Who will get the most from it
Shopping is its clear focus, and the scale of its audience suggests it has become a familiar option for many people: it has a 4.0 average from around 168,000 ratings, with over 10 million installs. That reach is reassuring in the sense that the app is established, but popularity is not a guarantee that every retailer or purchase will suit your needs. I’d still check the payment details at the point of sale rather than relying on assumptions from a previous order.
The strongest fit, in my view, is someone who shops with participating retailers, has predictable income, and wants a short, clearly tracked way to divide a purchase. It is less appealing if you prefer one payment and no ongoing reminders, or if your budget changes from week to week. Since the app deals with spending and payment information, I’d also use it deliberately on a device and connection I’m comfortable with, rather than making rushed financial decisions on an unfamiliar public network.
Final Thoughts
In a world where instant gratification often comes with a hefty price tag, Afterpay: Pay over time offers a refreshing alternative. Whether you’re a savvy shopper looking to spread out payments or someone who just wants to avoid credit card interest, this app is worth exploring.
Of course, with great power comes great responsibility. It’s important to remember that while the app makes purchases more accessible, it’s still crucial to keep track of your spending and ensure you can meet your payment obligations. If you can do that, I’d say this app is a fantastic tool to add to your financial toolkit.
So, if you’re ready to tackle that wishlist without the immediate financial burden, give Afterpay a try. You might just find yourself enjoying the flexibility and ease it brings to your shopping experience.
Highlights
- Easy to set up and use for all ages.
- No interest charges if paid on time.
- Wide range of partner retailers.
- Instant approval for most users.
- Syncs well with online shopping carts.
Limitations
- Late fees can accumulate quickly.
- Requires a credit/debit card to use.
- Limited to partnered stores only.
- May impact credit score if misused.
- Not available in all countries.
Frequently Asked Questions
01What is Afterpay and how does it work?
Afterpay is a buy-now-pay-later service that allows you to make purchases and pay for them in four equal installments, due every two weeks. It's interest-free, provided you make your payments on time. Once you download the app, you can shop online or in-store at partnered retailers, selecting Afterpay as your payment method at checkout.
02Is there a credit check involved with using Afterpay?
No, Afterpay does not perform a credit check when you sign up or use their service. This means your credit score won't be affected when you apply. Instead, Afterpay makes a decision based on your initial payment amount and other factors, ensuring a smooth and efficient process for users.
03Are there any fees associated with Afterpay?
Afterpay itself is free to use as long as you make your payments on time. However, if you miss a payment, a late fee is applied to your account. The late fees are capped, and Afterpay sends reminders to help you stay on track with your payment schedule.
04Can I use Afterpay for in-store purchases?
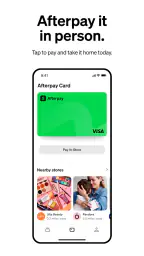
Yes, Afterpay can be used for in-store purchases at select retailers. To do this, you'll need to use the Afterpay app to set up a barcode or payment code, which the retailer will scan at checkout. This allows for a seamless shopping experience both online and offline.
05What happens if I can't make an Afterpay payment on time?
If you miss a payment, Afterpay will first attempt to collect the due amount from your linked card. If unsuccessful, a late fee is applied, and you’ll receive notifications to update your payment method or pay the overdue amount. Continued missed payments can lead to account suspension.


